The following graph shows the changes in global crude oil production since January 2001. This start year is being used to make the graph comparable to previous graphs which were based on EIA International Petroleum Monthly data (now discontinued) which started in that year. The present data source is the EIA International Energy Statistics with more detailed, country-by-country data, downloaded on 13/5/2012.
http://www.eia.gov/cfapps/ipdbproject/iedindex3.cfm
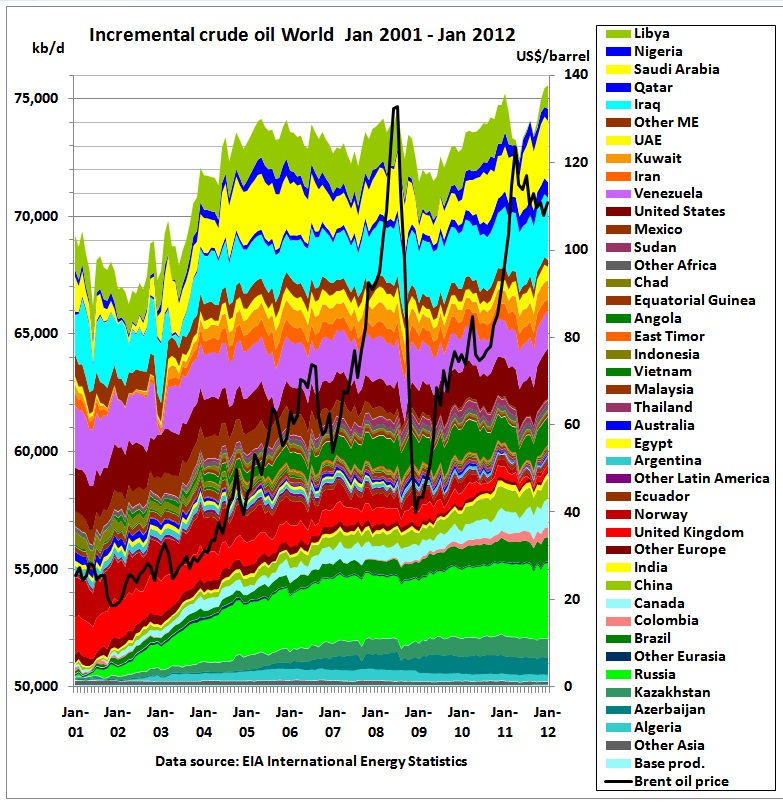
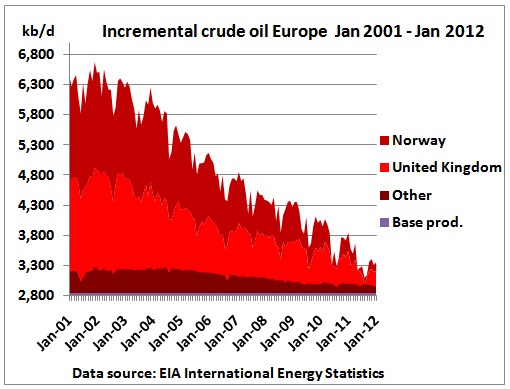
Russia, together with Kazachstan and Azerbaijan is on a production plateau for almost 2 years now. Brazil, Canada (syncrude from tar sands) and Colombia (heavy oil) are growing. China seems to have peaked end 2010. The North Sea continues to decline. Angola has peaked in the 1st quarter of 2010. The US was able to increase production (shale oil). Mexico is in decline. All said, in this group (growing, declining and peaking) production has increased by around 1 mb/d since 2004, basically driven by shale oil in the US and heavy oil in Colombia, both unconventional oil. Except for variations in the North Sea (annual maintenance cycle) and disruptions in the Golf of Mexico (hurricanes, accidents) the production of this group is fairly predictable over the short and medium term.
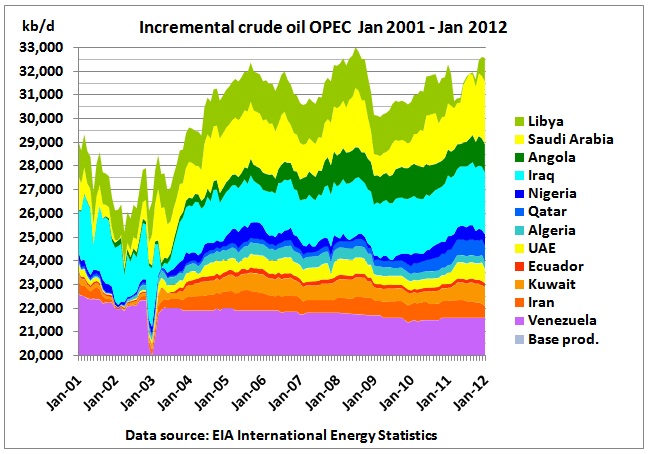
On top of this we have OPEC. Venezuela reports the same production figure for over a year now which makes this highly questionable. Iraq increased production by 500 Kb/d over 4 years, almost reaching pre-war levels. Most remarkable is Saudi Arabia’s production rebound after minimums in 2007 (genuine decline) and 2009 (GFC) to levels exceeding the oilympic peak in 2008, albeit by just 240 kb/d. So Saudi Arabia is still a swing producer, but with delays as was shown during the war in Libya. Very crucial for the world is Iran (geo-politics, socio-economic implications for a 70 million country) where crude production declined since mid 2011. On top of the graph is Libya, which is now recovering.
Incremental graphs by continent
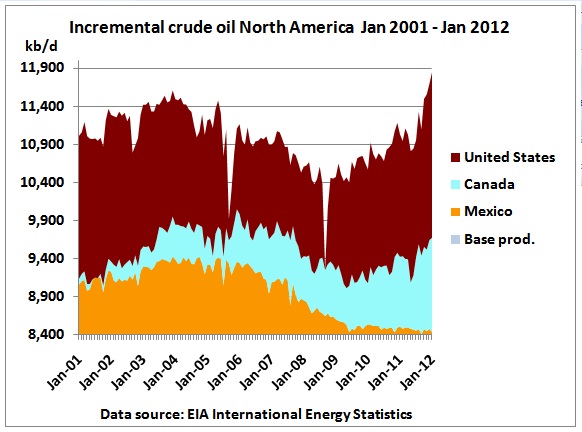
We see that syncrude from Canadian tar sands could not compensate yet for the decline in Mexico. US production is up from shale oil but that could change in the next hurricane season.
It is to be noted that EIA data may be too high. Petroleum geologist Jeff Brown from ASPO USA recently drew attention to data differences between the EIA and the Texas Rail Road Commission:
http://www.theoildrum.com/node/9182#comment-893312

The incremental graphs in this article will not be affected by higher reporting as long as it is at the same level over time. In 2011, however, we have an increase over the average of around 200 kb/d.
Even more importantly, EIA’s crude oil data are 3 mb/d higher than IEA’s due to different definitions of crude oil, in particular in relation to condensate and NGLs. A detailed post on this is necessary.
In Latin America:
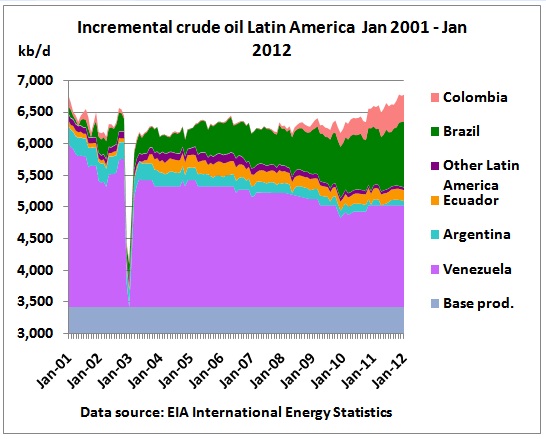
Venezuela features prominently here because of the low production during a strike end 2002 – beginning of 2003, giving the production profile a large variability. The long term production decline over the whole period was 1 mb/d. Growing production in Brazil could not offset decline in Venezuela and Argentina. Growth in Colombia from heavy oil brought production in Jan 2012 to same levels as in Jan 2001.
 Sans mots
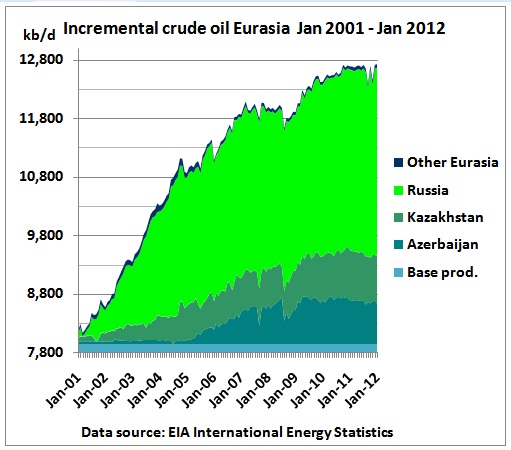
Without Russia the world would be in a much deeper oil crisis than now. The whole FSU group is on a plateau for around 2 years now
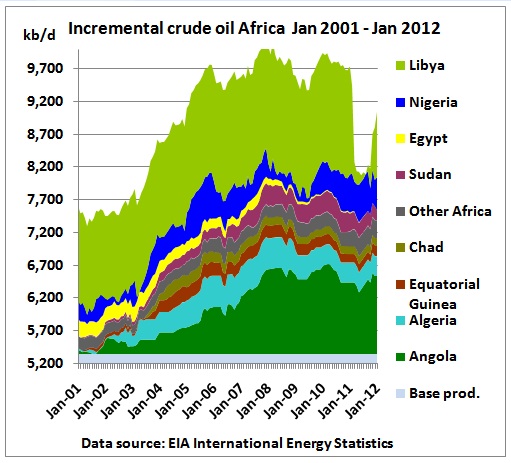
Africa without Libya is also on a bumpy plateau, mainly lifted up between 2004 and 2008 by Angola which couldn’t increase production for 4 years. Even if Libya is back to pre-war levels, production would still be 500 kb/d below peak levels in 2007.
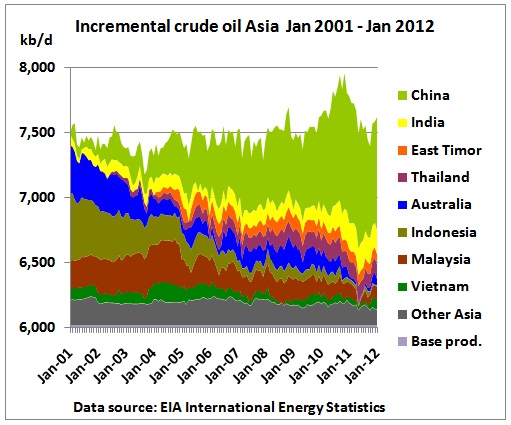
Very clear: decline in Vietnam, Malaysia, Indonesia and Australia. China offset that decline but peaked end 2010.
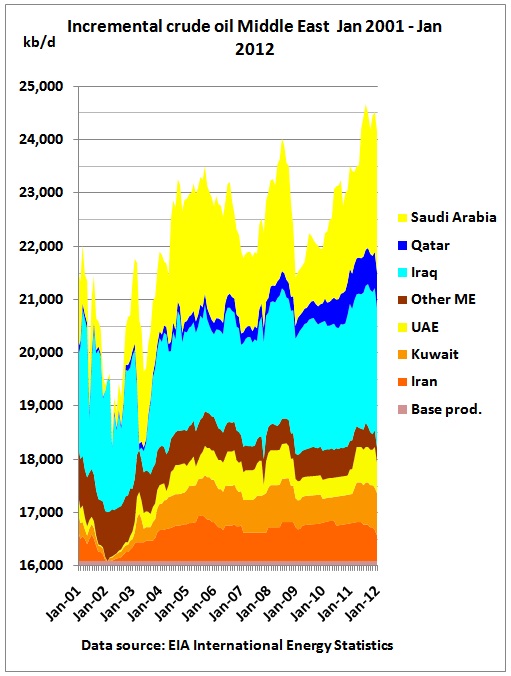
Continuing growth in Iraq and Qatar. Saudi Arabia delivered a modest increase of 240 kb/d over the oilympic peak in July 2008
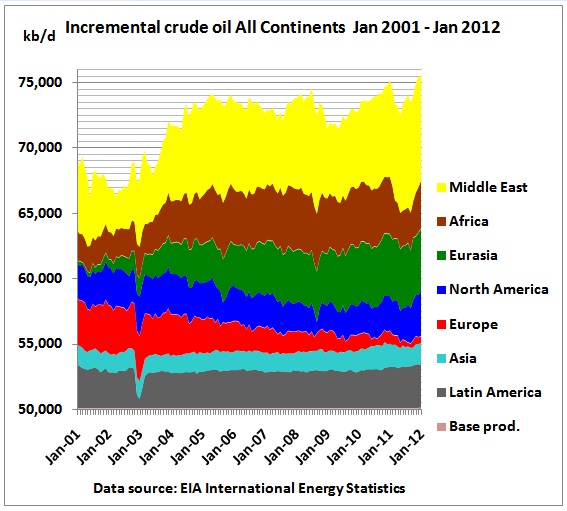
Incremental production by continent. There is not much change compared to previous reports. Latin America and Asia practically flat. Decline in the North Sea and earlier decline in North America offset by growth in Eurasia which now seems to be at peak. The Libyan production drop is clearly visible. It lasted much longer than the Venezuela strike, the Iraq war or hurricane events in the Gulf of Mexico.
Conclusion:
Any potential growth as seen in the past year or so depends on a handful of countries: Saudi Arabia, Qatar, Brazil, Colombia’s heavy oil, syncrude from Canadian tar sands, US shale oil. Iraq is a wild card and Iran is on its second and last oil peak, foreshadowing potential rivalries. In other words: desperate attempts are made to keep the oil flowing.